Upcoming Mentoring Sessions

Optional Doubt Session
RMS - World History & Post-Independence
RMS - Human & Economic Geography
RMS - Indian Society - Part II
RMS - Indian Society - Part I
News Reading Hour
RMS - Disaster Management
RMS - Environment
RMS - Internal Security - Part II
RMS - Internal Security - Part I
RMS - Social Justice - Part III
RMS - Social Justice - Part II
RMS - Social Justice - Part I
RMS - International Relations
RMS - Governance - Part II
RMS - Governance - Part I
Mentorship Program Introductory Session
RMS - Indian Physiography - Archipelagos of India
RMS - Indian Physiography - Coastal Plains of India
RMS - Art & Culture - Bhakti Movement
RMS - Polity - Elections & Political Parties
RMS - Indian Physiography - The Great Indian Desert
Step-Up RMS - Economic Survey and Budget : Part - 2
Step-Up RMS - Resources - Forests, Soils, Minerals etc : Part - 2
Step-Up RMS - Environment and Biodiversity Current Affairs : Part - 2
Step-Up RMS - History : 1935 - Independence
Step-Up RMS - Science and Technology Current affairs - Part - 2
Step-Up RMS - History : 1921 - 1935
RMS - A&C - Current Affairs
RMS - Indian Physiography - Peninsular Plateau
RMS - Polity - Services under the Union and the States & Pressure Groups
RMS - Economy - Balance of Payments
RMS - Economy - Trade & Important Government Schemes
RMS - Modern History - 1830 AD to 1857 AD
RMS - Economy - Fiscal Policy & Budgeting
RMS - Economy - Inflation
RMS - Polity - Local-Self Government & Co-Operative Societies
Step-Up RMS - Environment and Biodiversity Current Affairs : Part - 1
Step-Up RMS - Science and Technology Current affairs - Part - 1
Step-Up RMS -History : 1906 - 1920
Step-Up RMS - History 1857-1905
Step-Up RMS - Geomorphology - Types and Distribution
Step-Up RMS - Evolution + Interior of earth + oceanography
Step-Up RMS - History - Constitutional reforms
Step-Up RMS - Medieval History - kingdom chronology + terminology (Part - 2)
RMS - Indian Physiography - The Great North Indian Plain
RMS - Indian Physiography - Intro & The Himalayas
Step-Up RMS - Indian geography - location , landforms
Step-Up RMS - Drainage system + Rivers (India and world)
RMS - Art & Culture - South India
RMS - Economy - Taxation
RMS - Economy - Money and Banking - Part II
RMS - Polity - Union Legislature - Part III
Step-Up RMS – Indian Culture: Architecture + Literature (Part-2)
Step-Up RMS - Human geography
Step-Up RMS - Delhi sultanate + mughal administration
Step-Up RMS - Resources - Forests, Soils, Minerals etc
Step-Up RMS - Climatology + Indian monsoon
Step-Up RMS - Medieval History - kingdom chronology + terminology
Step-Up RMS - Indian school of philosophy -Buddhism & Jainism
Step-Up RMS - Indian Culture : Architecture + literature
Step-Up RMS - Ancient history - chronology + terminology
Step-Up RMS - Economic Survey and Budget
Step-Up RMS - Polity - Miscl-Imp Judgements , Amendments, Miscl concepts etc
Step-Up RMS - Agriculture and related concepts
Step-Up RMS - Polity - Constitutional and Non-Constitutional Bodies
Step-Up RMS - Economics - External Sector
Step-Up RMS - Polity - Judiciary- SC/HC/Lower courts
Step-Up RMS - Economics - Fiscal policy and Financial Markets
Step-Up RMS - Polity - Parliament and State Legislature
Step-Up RMS - Economics - Money and Banking
Step-Up RMS - Polity - Union and State Executives
Step-Up RMS - Economics - Basic Economics and Terminology
Step-Up RMS - Polity - State, Citizenship, FR/FD and Emergency Provisions
RMS - Polity - Judiciary - Part II
RMS - Geography - Biomes and Natural Resources
RMS - Economy - Money and Banking - Part I
RMS - Geography - Oceanography
RMS - Medieval History - 646 AD to 1192 AD
RMS - Art & Culture - Post Mauryan Period
RMS - Polity - Union Legislature - Part II
RMS - Economy - Financial Markets
RMS - Polity - Judiciary Part I
RMS - Polity - Separation of Powers & Federal System
RMS - Geography - Atmospheric Circulation
RMS - Polity - Union Legislature - Part I
RMS - Geography - Air Mass, Fronts & Cyclones
RMS - A&C - Pre-Historic to Mauryan Period
RMS - Economy - Fundamentals of Economy & NIA
RMS - Polity - Emergency Provisions
RMS - Geography - Humidity, Clouds & Precipitation
RMS - Economy - Demography, Poverty & Employment
RMS - Modern History - 1813 AD to 1857 AD
RMS - Polity - Union & State Executive
RMS - Modern History - 1932 AD to 1947 AD
RMS - Geography - Basics of Atmosphere
RMS - Polity - Fundamental Rights - Part III
RMS - Economy - Planning and Mobilisation of Resources
RMS - Modern History - 1919 AD to 1932 AD
RMS - Modern History - 1757 AD to 1813 AD
RMS - Economy - Financial Organisations
RMS - Geography - Major Landforms
RMS - Polity - Constitutional and Statutory Bodies
RMS - Geography - EQ, Faulting and Fracture
RMS - Polity - Fundamental Rights - Part II
RMS - Economy - Industry, Infrastructure & Investment Models
RMS - Polity - DPSP & FD
RMS - Economy - Indian Agriculture - Part II
RMS - Geography - Rocks & Volcanoes and its landforms
RMS - Geography - Evolution of Oceans & Continents
RMS - Polity - Fundamental Rights - Part I
RMS - Modern History - 1498 AD to 1757 AD
RMS - Modern History - 1858 AD to 1919 AD
RMS - Geography - Interior of the Earth & Geomorphic Processes
RMS - Geography - Universe and Earth and Basic concepts on Earth
RMS - Economy - Indian Agriculture - Part I
RMS - Economy - Fundamentals of the Indian Economy
RMS - Polity - Union & its territories and Citizenship
RMS - Polity - Constitution & its Salient Features and Preamble
Learning Support Session - ANSWER writing MASTER Session
Learning Support Session - How to Read Newspaper?
Mastering Art of writing Ethics Answers
Mastering Art of Writing Social Issues Answers
Answer Review Session
UPSC CSE 2026 Form Filling Doubt Session
Mentoring Session (2024 - 25) - How to Write an ESSAY?
Social Issues Doubts and Mentoring Session
Ethics & Essay Doubts and Mentoring Session
Geography & Environment Doubts and Mentoring Session
History Doubts and Mentoring Session
Economy & Agriculture Doubts and Mentoring Session
Online Orientation Session
LIVE NEWSPAPER READING SESSION
Mains Support Programme 2026-27
Mains Support Programme 2025- (1)
Polity & International Relations Doubts and Mentoring Session
Mentoring Sessions (2024-25) - How to DO REVISION?
Learning Support Session - How to Start Preparation?
RMS - Geography - World Mapping
Mentoring Session (2024-25) - How to Make Notes?
General Mentoring Session (GMS )
Mentoring Session (2025-26) - How to write an Answer?
Upcoming Live Classes






Current Affairs
Sept. 23, 2026
What is the Great Cormorant?
A Hyderabad-born Canadian birder spotted a rare leucistic Great Cormorant at Ameenpur Lake near BHEL recently.
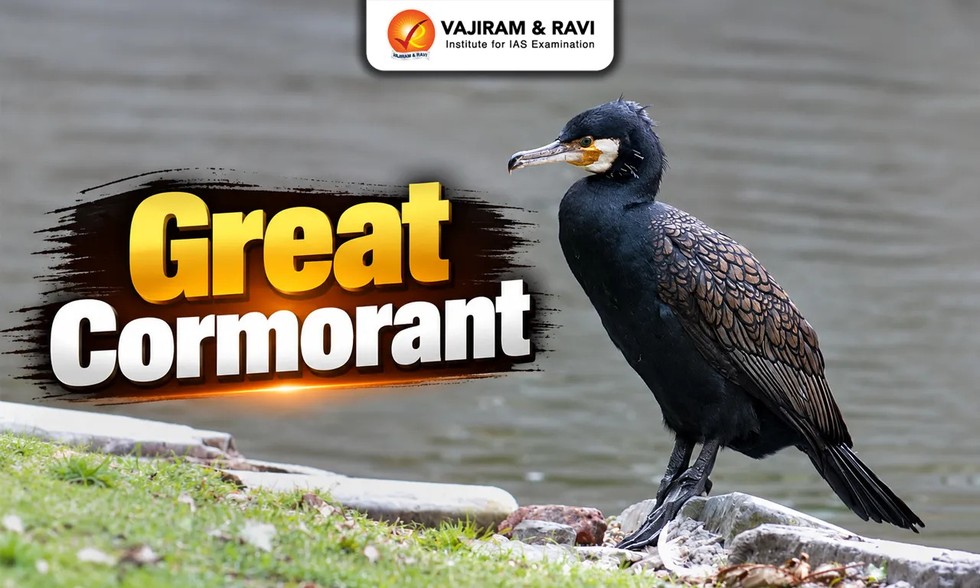
About Great Cormorant:
- It is a large waterbird and a member of the cormorant family of seabirds.
- Scientific Name: Phalacrocorax carbo
- Habitat and Distribution:
- They are probably the most widespread member of the cormorant family with a range that includes North America, Europe, Africa, China, India, Southeast Asia, New Zealand, Papua New Guinea and
- Well adapted to aquatic environments, they live in the shallow waters along marine shorelines but may inhabit lakes and rivers.
- Features:
- It is the largest member of the cormorant family.
- Males are typically larger and heavier than females.
- They have dark, glossy plumage, very long necks, long, hooked bills and webbed feet.
- Their powerful bills are greyish with white patches around its base.
- They employ their powerful webbed feet for efficient swimming and diving to catch a variety of prey, including fish, crabs, and, in some areas, frogs or ducklings.
- Conservation Status:
- IUCN Red List: Least Concern
Environment
Current Affairs
Sept. 23, 2026
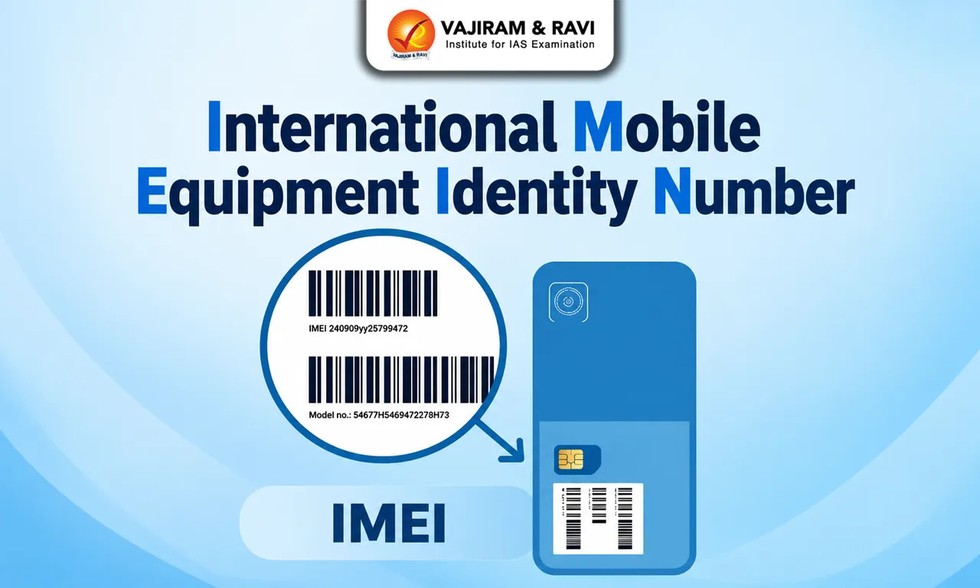
International Mobile Equipment Identity Number
India’s active wireless mobile subscriber base reached 1,204.01 million in July 2026 and it brings new security challenges i.e the misuse of the International Mobile Equipment Identity (IMEI) number or IMEI tampering.
About International Mobile Equipment Identity Number:
- It is a unique 15-digit number that identifies a mobile device on a telecom network.
- The first eight digits of an IMEI form the Type Allocation Code (TAC), which identifies the device model or type.
- Allocation of IMEI numbers: The Global System for Mobile Communications Association (GSMA) oversees the global allocation of TAC.
- GSMA allocate TACs to manufacturers and brand owners. Manufacturers then assign unique IMEIs to individual devices.
- A dual-SIM phone generally has two IMEI numbers, one for each SIM slot.
- Identification: Users can dial *#06#on their mobile device to display its IMEI number.
- India's IMEI Ecosystem:
- Manufacturers: They must register the IMEI numbers of all applicable telecom devices manufactured in India with the Government before their first sale, testing, research or other use.
- Registration is carried out through the Device Setu–Indian Counterfeited Device Restriction (ICDR) portal.
- Importers: They must register IMEI numbers on Indian Counterfeited Device Restriction (ICDR) portal with the Central Government before importing applicable telecom equipment into India.
- Resellers and retailers: They also must ensure that telecom devices offered for sale have valid and untampered IMEI numbers.
- Brand owners: They must ensure that devices sold under their brands comply with applicable IMEI registration and cybersecurity requirements.
- India’s legal framework to protect the telecommunication ecosystem:
- The Telecommunications Act, 2023: It provides stringent action against tampering with telecommunication identifiers, including the IMEI number of mobile handsets and other telecommunication devices.
- Section 42(3)(c)prohibits tampering with telecommunication
- Section 42(3)(e)prohibits obtaining Subscriber Identity Modules (SIMs) or telecommunication identifiers through fraud, cheating or impersonation.
- Violations may attract imprisonment for up to three years, a fine of up to ₹50 lakh, or both. Such offences are cognizable and non-bailable under Section 42(7) of the Act.
- Under Section 42(6), persons who abet or promote the commission of such offences are also liable to the same punishment.
- The Telecommunications Act, 2023: It provides stringent action against tampering with telecommunication identifiers, including the IMEI number of mobile handsets and other telecommunication devices.
Source : IMEI Tampering
Science & Tech
Current Affairs
Sept. 23, 2026
National Single Window System
The National Single Window System marks a significant step towards creating a transparent, and technology-driven regulatory ecosystem.
About National Single Window System:
- It serves as a digital platform that guides investors in identifying and applying for the approvals required for their businesses.
- It was launched in
- It is implemented by the Department for Promotion of Industry and Internal Trade (DPIIT), Ministry of Commerce & Industry.
- It integrates approvals offered by Central Ministries, State Governments, and regulatory authorities on a common digital platform.
- Key Functionalities of NSWS:
- Know Your Approvals: It is the Know Your Approvals (KYA) module, a tool that identifies the approvals applicable to a business based on its proposed activities.
- The portal hosts applications for approvals from 32 Central Ministries/ Departments and 34 State Governments and Union Territories.
- Common Registration Form: It captures information through a single interface and enables reuse of information across applications.
- Access to State Single Window Systems: It offers seamless access through a dedicated State Registration Form, ensuring integration with State-level approval mechanisms.
- Applicant Dashboard: It includes an applicant dashboard for submitting applications, monitoring their status, and responding to departmental queries.
- A centralized Document Repository enables one-time upload and reuse of documents across multiple approvals, reducing duplication of submissions.
- E-Communication Module: It facilitates online exchange of queries and clarifications between applicants and the concerned Ministries and State Governments.
- Significance:
- It simplifies the approval process by enabling one-time submission of information and documents.
- It helps reduce compliance and approval timelines.
- It also enhances transparency through real-time application tracking and online communication with regulatory authorities.
- NSWS minimizes duplication of information across departments and improves coordination among government agencies through an integrated digital ecosystem.
Source : National Single Window System
Polity & Governance
Current Affairs
Sept. 23, 2026
Oxyserphus narendrani
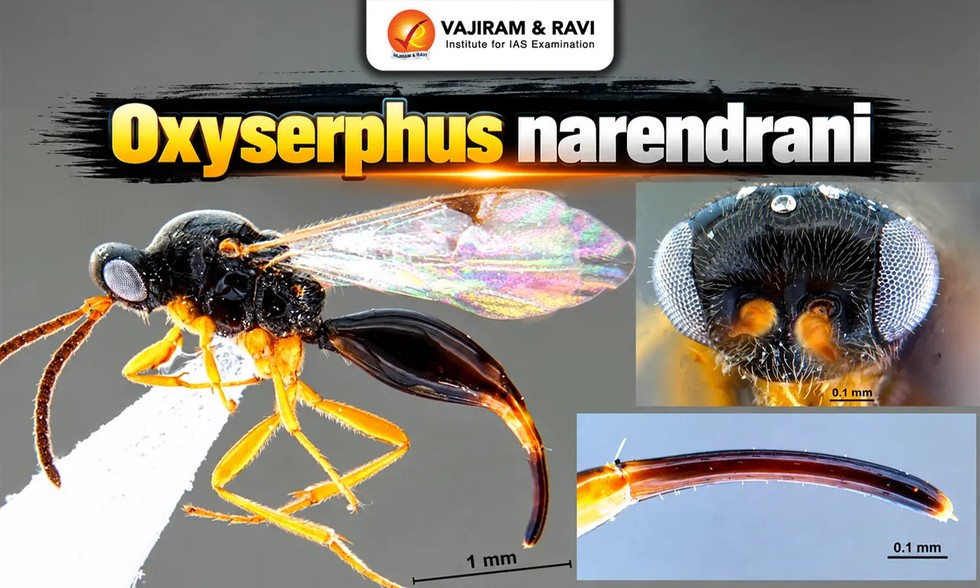
Researchers discovered the tiny insect in Dibru-Saikhowa National Park and named it Oxyserphus narendrani.
About Oxyserphus narendrani:
- It is a new species of parasitic wasp discovered in Dibru-Saikhowa National Park Assam.
- The members of the Oxyserphus genus are incredibly rare in insect collections globally and are typically only found in high-altitude areas.
Key Facts about Dibru-Saikhowa National Park
- Location: It is located in the Dibrugarh and Tinsukia districts of Assam.
- It was originally created to help conserve the habitat of the rare white-winged wood duck.
- Rivers: The Park is bounded by the Brahmaputra and Lohit Rivers in the north and Dibru River in the south.
- Vegetation: It mainly consists of moist mixed semi-evergreen forests, moist mixed deciduous forests, canebrakes and grasslands. It is the largest salix swamp forest in north-eastern India.
- Climate: It has a tropical monsoon climate with a hot and wet summer and cool and usually dry winter.
- Flora: It mainly consists of Hollong, Nahor, Simul, Sissoo, Khair, and Jamun are commonly found.
- Fauna: Asian Elephant, Wild Water Buffalo, Leopard, Clouded Leopard, Fishing Cat, Jungle Cat, Hog Deer, Sambar Deer, and Barking Deer are commonly found.
Environment
Current Affairs
Sept. 23, 2026
Exercise Tarang Shakti 2026
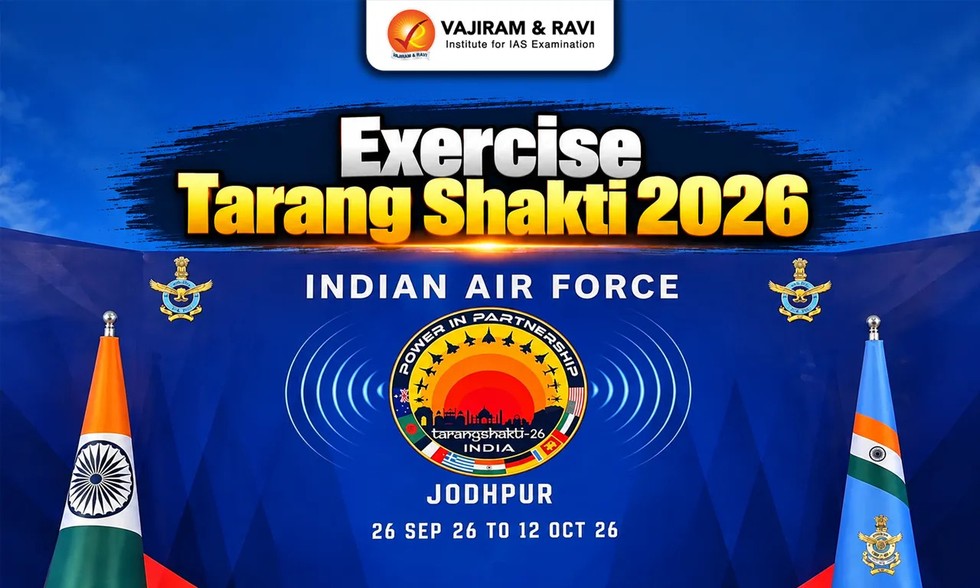
The Indian Air Force (IAF) will host the second edition of its largest-ever multinational air exercise, Tarang Shakti-26 in Jodhpur.
About Exercise Tarang Shakti 2026:
- It is the multinational air exercise to be conducted in Jodhpur.
- Participating Countries: Eight friendly foreign countries such as Australia, Bangladesh, France, Germany, Greece, Sri Lanka, UAE and USA will participate with air assets, while 32 nations will be attending as observers.
- Aim: It is aimed at enhancing interoperability among participating air forces, while providing a platform for exchanging operational experience and showcasing India’s air combat capabilities.
- The exercise will see the participation of advanced combat aircraft, including the U.S. Air Force’s F-35, the French Rafale, the UAE’s F-16 and a Bangladeshi C-130J.
- The IAF will field a range of its frontline platforms, including the Rafale, Mirage-2000, Jaguar, Tejas, MiG-29 and Su-30MKI.
Science & Tech
Current Affairs
Sept. 23, 2026
Lord Howe Island
A 16-year study from Lord Howe Island found record levels of plastic ingestion in fledgling sable shearwaters.
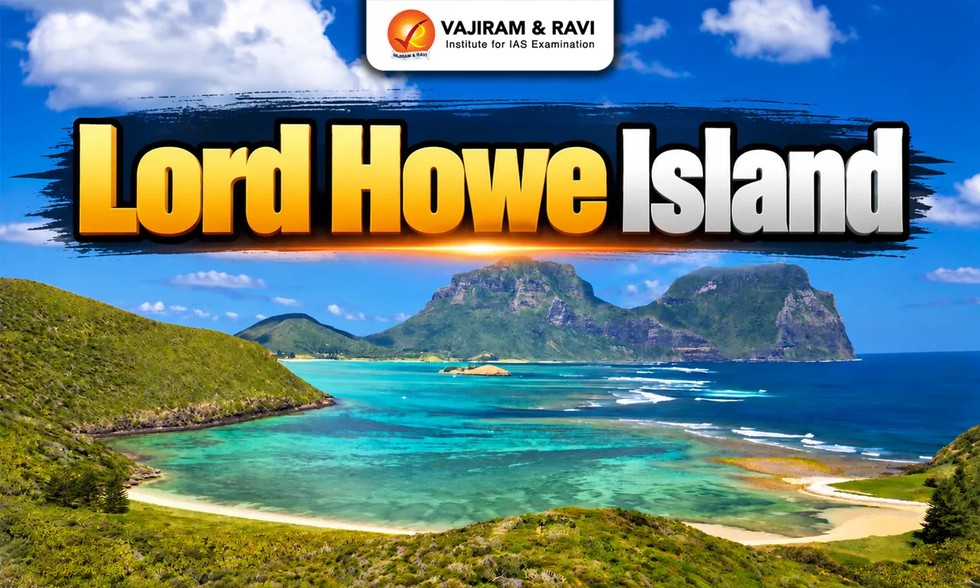
About Lord Howe Island:
- It is a crescent-shaped, volcanic island.
- Discovered By: It was discovered in 1788 and named for Admiral Lord Howe by Lieutenant Henry Lidgbird Ball of the British navy.
- Flora and Fauna:
- About 47% of the island's vascular plants are endemic, including the famous Kentia Palm (Howea forsteriana).
- It has endemic species like the Lord Howe Island Phasmid which is considered the world’s largest stick insect, and the flightless Lord Howe Woodhen (Gallirallis sylvestris).
- It hosts the world’s largest known population of sable shearwaters.
- The Lord Howe Island Group is a UNESCO World Heritage Site that boasts countless unique plants and animals, many of which are endemic to the region.
Geography

Article
23 Sep 2026
Using Trade Treaty Policy to Strengthen Arbitration
Context
- India’s expanding network of Bilateral Investment Treaties (BITs) and Free Trade Agreements (FTAs) reflects its efforts to deepen economic integration, attract investment and expand international market access.
- Recent agreements with the UAE, Israel, Uzbekistan, UK, EFTA, Oman and New Zealand demonstrate this growing engagement.
- Their importance, however, extends beyond tariffs and investment protection to commercial dispute resolution and arbitration.
- For international investors, the attractiveness of an economy depends not only on market opportunities but also on what happens when commercial relationships break down.
- India can therefore use its treaty framework to strengthen its domestic arbitration ecosystem and establish itself as a credible international arbitration jurisdiction.
The Opportunity Beyond Market Access
- The Arbitration and Conciliation Act, 1996 provides the statutory foundation for domestic arbitration, international commercial arbitration and enforcement of foreign awards.
- The challenge is to connect this framework more effectively with India's international treaty policy.
- India’s recent FTAs have generally omitted Investor-State Dispute Settlement (ISDS), reflecting concerns about regulatory autonomy and potential claims against the State.
- However, substantial foreign investment occurs through contracts between investors and Indian government agencies.
- In such cases, commercial arbitration can provide an alternative to ordinary court litigation.
- Future FTAs could clarify that the absence of ISDS is supported by the availability of effective commercial arbitration remedies in India.
- Such clarity would reassure investors while preserving India’s reservations concerning international investment arbitration.
Distinguishing ISDS from Commercial Arbitration
- India’s BITs increasingly distinguish treaty-based investment arbitration from contractual commercial arbitration.
- The India-Uzbekistan BIT, for example, excludes disputes arising solely from contractual breaches from ISDS.
- Greater clarity is required regarding local-remedy requirements. Some BITs require investors to approach domestic courts or administrative bodies before initiating international arbitration.
- Commercial arbitration seated in India should potentially be recognised as another legitimate mechanism for addressing investment-related contractual disputes.
- Future BITs could therefore clarify that pursuing a dispute through Indian commercial arbitration may satisfy applicable local-remedy requirements.
- This would better integrate domestic arbitration into India’s investment-protection architecture while avoiding unnecessary procedural uncertainty.
Third-Party Funding: A Need for Nuance
- Third-party funding allows external financiers to bear arbitration costs in return for an agreed financial interest in the outcome.
- India’s reservations about such funding in ISDS are understandable because investment disputes involve sovereign decisions and may affect regulatory policymaking.
- However, these concerns do not necessarily apply to ordinary commercial disputes.
- Restrictions on third-party funding in ISDS should therefore not automatically imply its prohibition in domestic commercial arbitration.
- India could develop a comprehensive regulatory framework covering disclosure, conflicts of interest, transparency and procedural fairness.
- A clear distinction between ISDS funding and commercial arbitration funding would help create a more mature arbitration ecosystem.
The Evaluation Parameters of Investors
- Investors evaluate economies on more than taxation, tariffs and market access. They also consider whether disputes can be resolved predictably and efficiently.
- A strong investment environment requires three interconnected elements:
- Prevention of disputes through clear treaties and contracts.
- Efficient arbitration proceedings that resolve disputes fairly and promptly.
- Predictable judicial enforcement of arbitral awards.
- India does not need to transform every BIT or FTA into an arbitration agreement.
- Instead, treaties should complement domestic reforms and clearly establish the relationship between ISDS, courts and commercial arbitration.
India as a Global Arbitration Hub
- India’s ambition to become a global arbitration hub requires consistency between treaty policy, legislation, judicial practice and institutional capacity.
- A credible arbitration ecosystem can reduce commercial uncertainty, strengthen investor confidence and facilitate long-term contracts.
- At the same time, appropriate safeguards are necessary to protect legitimate governmental regulation and prevent excessive claims against the State.
- The objective should therefore be a balanced system that protects commercial interests without compromising regulatory autonomy.
Conclusion
- India’s growing BIT and FTA network provides an opportunity to integrate trade, investment protection and dispute resolution more effectively.
- The absence of ISDS in some agreements need not create a legal vacuum if commercial arbitration in India is made credible, accessible and predictable.
- Future treaties should distinguish investment disputes from contractual disputes, clarify the relationship between local remedies and Indian-seated arbitration, and separate restrictions on ISDS funding from the potential use of third-party funding in commercial arbitration.
Editorial Analysis
Article
23 Sep 2026
SSA 5000 - Sustainability Assurance and the Fight Against Greenwashing
Why in the News?
- The Institute of Chartered Accountants of India (ICAI) has issued the Standard on Sustainability Assurance (SSA) 5000, aligned with the International Standard on Sustainability Assurance (ISSA) 5000, with certain provisions tailored to the Indian context.
- The standard will become effective from April 1, 2027, and seeks to bring greater rigour, consistency and credibility to corporate sustainability disclosures.
What’s in Today’s Article?
- About Sustainability Assurance (Meaning, Features, Greenwashing, Verification of Claims, Challenges, Opportunities, Significance)
About Sustainability Assurance
- Sustainability assurance refers to the independent examination and verification of information disclosed by companies regarding their environmental, social and governance (ESG) performance.
- Unlike financial statements, which are generally prepared and audited according to established accounting and auditing standards, sustainability information can be collected through different methodologies and may involve both measurements and estimates.
- This creates challenges relating to consistency, comparability, data quality and verification.
- SSA 5000 seeks to address these concerns by establishing principles and procedures for assurance practitioners to:
- Examine sustainability disclosures
- Assess relevant risks
- Collect and evaluate evidence
- Examine internal controls
- Identify material misstatements
- Issue an assurance conclusion
What Does SSA 5000 Cover?
- The framework covers sustainability information across a wide range of ESG parameters. These may include:
- Greenhouse gas emissions
- Energy consumption
- Water usage
- Waste management
- Biodiversity impacts
- Diversity and employee practices
- Governance indicators
- The standard replaces earlier ICAI standards such as SSAE 3000 and SAE 3410, which provided an umbrella framework for sustainability assurance engagements.
- Its introduction comes at a time when companies are reporting sustainability information under multiple frameworks, including Business Responsibility and Sustainability Reporting (BRSR), Global Reporting Initiative (GRI) and International Sustainability Standards Board (ISSB) standards.
SSA 5000 and Greenwashing
- A major concern in sustainability reporting is that companies themselves prepare their sustainability reports and determine which achievements to highlight.
- SSA 5000 introduces a greater role for an independent assurance practitioner, who must assess whether sustainability claims are supported by adequate evidence and whether disclosures contain material errors or misleading presentations.
- For example, if a company claims that it has reduced its carbon emissions by a particular percentage, the assurer would examine:
- Emission-related calculations
- Energy consumption records
- Supporting documentation
- Relevant internal processes and controls
- This shifts sustainability reporting from management assertions towards evidence-based disclosures.
Addressing Selective Disclosure
- Greenwashing is the practice of making misleading or exaggerated claims about a company’s environmental or sustainability performance to appear more eco-friendly than it actually is.
- Example: A company markets itself as “carbon neutral” while achieving little actual reduction in its emissions.
- Greenwashing may also occur through selective disclosure or “cherry-picking”, where positive sustainability achievements are highlighted while negative information is omitted.
- SSA 5000 requires assurance professionals to assess whether disclosures provide a balanced picture.
- They must consider whether the reporting scope excludes significant operations or negative information that could influence stakeholder decisions.
- The framework also addresses sustainability impacts across the wider value chain. A company may report improvements in its own operations while excluding emissions or social impacts generated by suppliers and other parts of its value chain.
- Assurance practitioners must therefore assess whether reporting boundaries are appropriate and whether significant activities have been excluded without adequate justification.
Verification of Sustainability Claims
- SSA 5000 requires assurance professionals to critically examine management assumptions rather than simply accepting explanations provided by companies.
- For instance, a claim of “carbon-neutral operations” may require examination of how emissions have been calculated, whether carbon offsets are genuine and whether claimed emission reductions are permanent.
- This is particularly important because sustainability information often involves technical calculations, estimates and measurement methodologies.
- The framework therefore requires practitioners to assess data quality, understand measurement processes and undertake procedures to verify the information.
Challenges in Implementation
- Complex Supply Chains
- Assessing sustainability impacts across multiple suppliers and business partners can be difficult, particularly when companies lack reliable data from their wider value chains.
- Lack of Standardised Data
- Differences in data collection and measurement methodologies can make sustainability information difficult to compare across companies.
- Forward-Looking Claims
- Claims relating to Net Zero targets and future climate commitments involve assumptions about future actions, technology and business decisions, making their assurance more complex.
- Shortage of Skilled Professionals
- Sustainability assurance requires multidisciplinary expertise covering accounting, auditing, environmental science and technology. A shortage of professionals with this combination of skills could constrain implementation.
- Higher Compliance Costs
- Companies may need to invest in data-management systems, technology and specialised personnel to make sustainability information assurance-ready. These costs could be particularly significant for smaller firms.
Opportunities
- The emergence of sustainability assurance can create demand for professionals and firms capable of integrating accounting, assurance, environmental expertise, technology and regulatory advisory services.
- The sustainability consulting market has already expanded following SEBI's introduction of BRSR requirements for listed companies.
- SSA 5000 could therefore contribute to the emergence of integrated sustainability-management firms that help companies collect reliable data, prepare disclosures and meet assurance requirements.
Environment & Ecology